

Best Bonded Warehouse Management Software UK: 2026 Buyer's Guide
- John Hall
- Customs Specialist at iCustoms.ai
Bonded warehouse management software maintains the stock account for a customs or excise warehouse: duty status per consignment, declarations on entry and release, and an audit trail HMRC can inspect. In the UK it is a regulated system, not a free choice of tool.
That last point reshapes the whole evaluation, and it is missing from most buyer’s guides on this subject. Search best customs warehouse software 2026 and you will mostly find ranked lists that date within months. The criteria below are derived instead from what HMRC actually requires of the system, which means they survive the market changing and you can apply them to any supplier including ours. Cost is handled separately, because it deserves more than a paragraph.
What you are actually buying: the duty layer
Before comparing anything, be clear which product category you are shopping in, because two very different systems get described with overlapping language.
A warehouse management system handles locations, putaway, picking, despatch and labour. A duty management system handles duty status, procedure, declarations and the stock account. HMRC names both separately in its customs warehouse application requirements and asks for evidence of each, telling applicants to include both if you use both.
So bonded warehouse management software is the second layer. It does not replace your fulfilment system and it is not competing with one. If your shortlist currently mixes both categories, split it before going further. Our guide for 3PLs and multi-client operators explains the distinction in more detail.
Within the duty layer, the market splits again. Customs warehouse software UK suppliers sell tends to cover customs warehousing only. Dedicated excise warehouse software covers excise only. Fewer products cover both, which matters because a business importing alcohol or tobacco typically needs both approvals on the same premises and therefore needs one reconciled position across them.
One more piece of vocabulary to unpick before you start comparing. HMRC compliance software is used loosely to describe anything from a declaration filing tool to a full duty management system, and the two are not interchangeable. A filing tool produces declarations. A duty management system maintains the stock account those declarations are made against, and HMRC treats it as part of that account. Establish which one a supplier is selling in the first ten minutes of any conversation.
Why HMRC approval comes before every other criterion
This is the criterion almost every buyer’s guide omits, and it can invalidate a shortlist.
HMRC guidance on customs warehousing
“Software that has not been approved by HMRC cannot be used.” A duty management system that cannot meet HMRC’s stated requirements will not be approved for customs warehousing purposes. And the responsibility and accuracy of the system lies with the warehousekeeper, not the software supplier.
Read the last sentence again, because it changes what you are buying. You cannot transfer accountability to a vendor by purchasing their product. If the system produces a wrong duty figure, that is your assessment. So the question to a supplier is not “are you HMRC approved” as a badge, it is “can your system demonstrably meet the conditions my authorisation is granted against, and can you help me evidence that”.
One specific requirement is worth carrying into every vendor conversation because almost nobody asks it. Before a closing stock balance system is authorised, it must be tested to confirm it can handle the proposed volume of goods, and the warehousekeeper should provide evidence that the testing took place. Ask how a supplier supports that evidence. A vendor who has done it before will answer immediately.
The full picture of what HMRC assesses, and what it checks on a visit, is in our guide to HMRC bonded warehouse audits.
Nine evaluation criteria for bonded warehouse management software
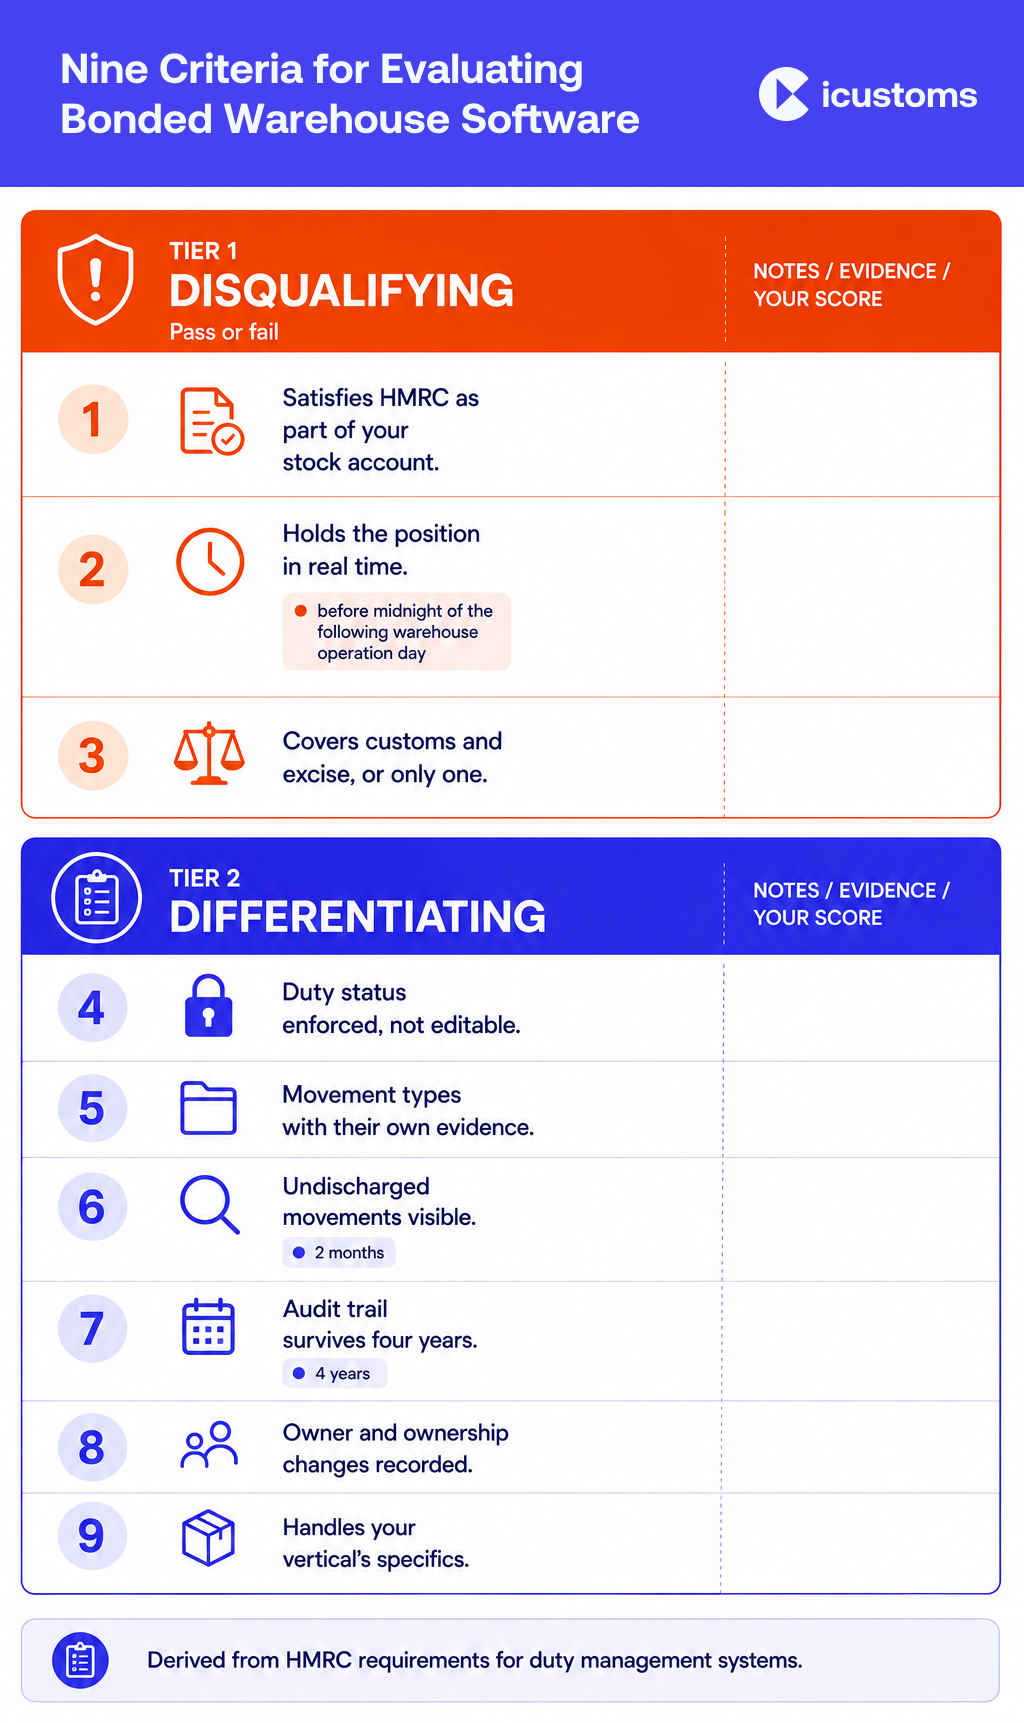
Apply these in order. The first three are disqualifying, the rest are differentiating.
- Can the bonded warehouse management software satisfy HMRC as part of your stock account? Not a marketing claim but a functional test. The system must permit a full audit of the warehousing arrangements including physical examinations, allow documentation for goods released to free circulation to be checked and related to the goods, and contain everything needed for the operation, validation and integrity of the arrangements alongside your commercial records. HMRC regards those commercial records and the duty management system as one system that together constitutes the stock account, so integration between them is not optional.
- Does it hold the position in real time? The standard requirement is that customs warehouse stock records must always show the current stock under the procedure. Where a duty management system supports a commercial system, records must be updated as soon as information becomes available and no later than before midnight of the following warehouse operation day. You must also be able to bring the stock position current at an officer’s request. Ask any vendor to demonstrate that, not describe it.
- Does the warehouse management software cover customs and excise, or only one? A customs warehouse suspends customs duty and import VAT. An excise warehouse suspends excise duty on alcohol, tobacco, energy products and, from 1 October 2026, vaping products. Businesses importing excise goods commonly need both approvals on one site. Two systems means reconciling them by hand, which puts the error back exactly where the approvals were meant to remove it.
- Is duty status enforced rather than editable? Where duty-suspended and duty-paid goods share a site, that is co-storage, it needs HMRC permission, and the system must identify the location and duty status of all goods at all times and ensure duty-paid goods cannot revert to duty-suspended without payment of duty. That is a software specification. Ask to see the control, and ask whether the transition is logged.
- Are movement types distinguished, with their own evidence? Receipt, removal to home use, release to free circulation, onward duty-suspended movement, transfer between sites, export by destination, Northern Ireland movements and miscellaneous duty-free removals each carry different duty treatment and different evidence. A single movement list with a free-text note cannot be audited. Neither can it be relied on.
- Can you see undischarged movements before they become a disclosure? Duty-suspended movements stay open until discharged, and any dispatch not discharged after two months must be reported on the W1 excise warehouse return. Continuous visibility of open items is the difference between managing that and discovering it at period end.
- Will the audit trail survive four years? Customs warehouse records must be kept for a minimum of four years after the goods have been discharged from the procedure. The practical question is not storage but retrieval: can you produce the full history of one named consignment, with who changed what and when, years after the event, without reconstruction.
- Does it record owners and ownership changes? Essential for anyone holding third-party stock. Stock records must accurately record any change of ownership and full details of owners storing goods must be available to HMRC. Ownership can transfer while a pallet never moves, and the record has to follow the change rather than the goods.
- Does it handle your vertical’s specifics? Generic capability is not enough where the duty base is unusual. Alcohol is taxed on litres of pure alcohol, so strength must be held and maintained per batch, and Small Producer Relief is fixed at the production date rather than the duty point, meaning the production year and the rate that applied then must travel with the stock. Tobacco, energy products and, from October 2026, vaping products each bring their own requirements.
Criteria 3, 6 and 9 are where the cluster’s detail pays off. If you want the underlying rules rather than the summary, see the customs versus excise comparison, the excise authorisation and W1 returns guide, and the alcohol duty warehousing guide.
Stock control under bond is not ordinary stock control
Worth separating out, because it is the assumption that trips up buyers coming from a general warehousing background.
Ordinary stock control answers how much you have and where it is. Stock control in a bonded warehouse has to answer a further question on every line: what is owed on this, to whom, and has it been paid. That turns a quantity into a tax position, and it changes what the record has to hold.
- Quantity alone is insufficient. For alcohol the tax base is litres of pure alcohol, so strength has to be held and maintained rather than noted once.
- Identical goods are not interchangeable. Two pallets of the same product acquired under different consignments can carry different duty positions, preferences or relief rates, so stock cannot be pooled by product code.
- Status is not derived from location. Duty-suspended and duty-paid stock can sit side by side under co-storage, so status has to be an attribute of the goods, not of the bay.
- History is part of the record. An ordinary stock system can overwrite a balance. A bonded stock account has to show how the balance was reached, for four years after discharge.
If a shortlisted product treats duty as a field bolted onto a conventional inventory model, these four points are where that shows up, usually during the first reconciliation rather than during the demo.
Capability comparison: how the market divides
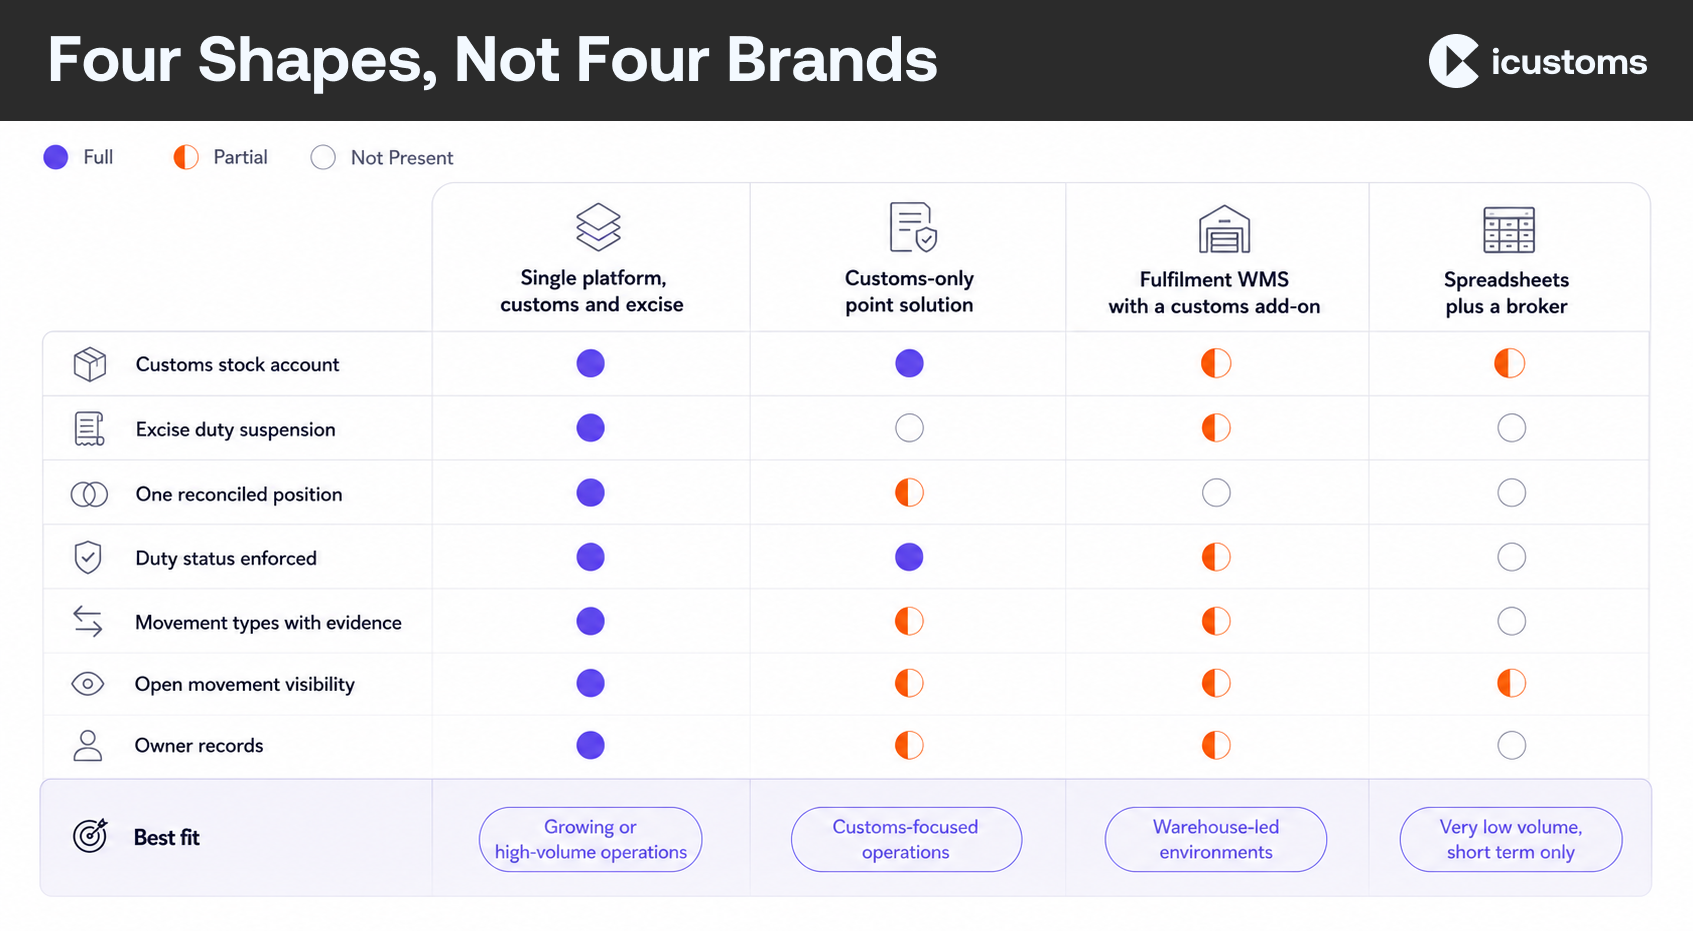
Rather than ranking named products, which dates within months, compare the shapes available. Most shortlists contain two or three of these.
| Feature | Single platform, customs and excise | Customs-only point solution | Fulfilment WMS with a customs add-on | Spreadsheets plus a broker |
|---|---|---|---|---|
| Customs warehouse stock account | Yes | Yes | Varies, often partial | Manual |
| Excise duty suspension | Yes | No | Rarely | Manual |
| One reconciled position across both | Yes | Not applicable | No, two systems | No |
| Duty status enforced per consignment | Yes | Usually | Often a field, not a control | No |
| Movement types with evidence | Yes | Usually | Varies | No |
| Open movement visibility | Yes | Varies | Rarely | No |
| Owner and ownership change records | Yes | Varies | Varies | Manual |
| Best fit | Sites holding both approvals, or excise goods | Customs-only importers with no excise exposure | Operations where fulfilment dominates and duty volume is low | Very low volume, short term only |
Table: capability comparison of bonded warehouse management software shapes, structured around buyer criteria rather than named vendors.
The fourth column deserves a word, because it is where a surprising number of operations still sit. Spreadsheets plus a customs broker can work at genuinely low volume. What it cannot do is show the current position on demand, enforce duty status, or produce a four-year retrievable history, which is why it stops working precisely when the business becomes worth auditing.
Integrations that actually matter
Integration questions are where vendor conversations get vague, so be specific about which connections change your workload.
CDS integration. Customs declarations run through the Customs Declaration Service. What matters is whether entry and release declarations are produced from the same stock record that holds the goods, or whether someone re-keys between two systems. Re-keying is where duty errors originate.
EMCS integration. Duty-suspended excise movements are recorded on EMCS. Ask precisely what a supplier means by EMCS integration: whether movement records are held alongside your stock so open items are visible, or whether the platform submits, and if so what exactly. Vague answers here are common and worth pressing on.
ERP integration. Your finance system needs the duty position, and your duty system needs purchase and sales data. Ask about the direction of flow, the mechanism, and who owns the mapping. An ERP that receives a monthly CSV is integrated in name only.
Warehouse management system. If you run one, the duty layer has to reconcile against it rather than duplicate it. HMRC expects both and treats the combination as your stock account.
Document capture. Trade documents arrive in every format imaginable, particularly if you hold third-party stock. Whether the platform extracts and validates data from source documents, or expects you to type it, is one of the largest differences in ongoing workload between otherwise similar products.
One further question worth asking about any integration: if a third party operates part of your system, you must always have access to its records, preferably view-only access or daily reporting of receipts, deliveries, adjustments and balances. Outsourcing the system does not outsource the obligation.
Questions to ask any vendor
Take these into a demo. They are deliberately awkward, and the quality of the answers will separate your shortlist faster than a feature matrix.
- Show me the current stock position for one consignment, then show me its full history including who changed what.
- How does your system prevent duty-paid stock being shown as duty-suspended without payment?
- Which movement types do you distinguish, and what evidence does each require?
- Show me every duty-suspended movement currently open, and how long each has been open.
- How do you support evidencing volume testing for authorisation?
- What exactly do you mean by CDS integration, and by EMCS integration? Describe the mechanism.
- If HMRC asked me to bring the stock position current during a visit, what would I do?
- How is data segregated if I hold stock for multiple owners?
- What happens to my records after four years, and how do I retrieve one consignment from year three?
- Who is accountable if the system produces a wrong duty figure?
That last question has one correct answer, and a supplier who claims otherwise has misunderstood the regime. The responsibility sits with the warehousekeeper. What a good supplier offers is a system that makes discharging that responsibility straightforward, plus the expertise to help you evidence it.
Red Flags
- An HMRC approval badge presented as a product certification. Approval attaches to your arrangements as warehousekeeper, and any claim implying otherwise should be probed hard.
- Duty status as an editable field with no logged transition.
- “Real time” that means overnight batch. Ask what happens at 3pm on a Tuesday.
- Excise support that turns out to mean a report you export and rekey.
- No answer on volume testing.
- Customs and excise handled in separate modules that reconcile monthly rather than continuously.
- Reluctance to demonstrate on your data rather than a prepared demo set.
Where iWarehouse fits
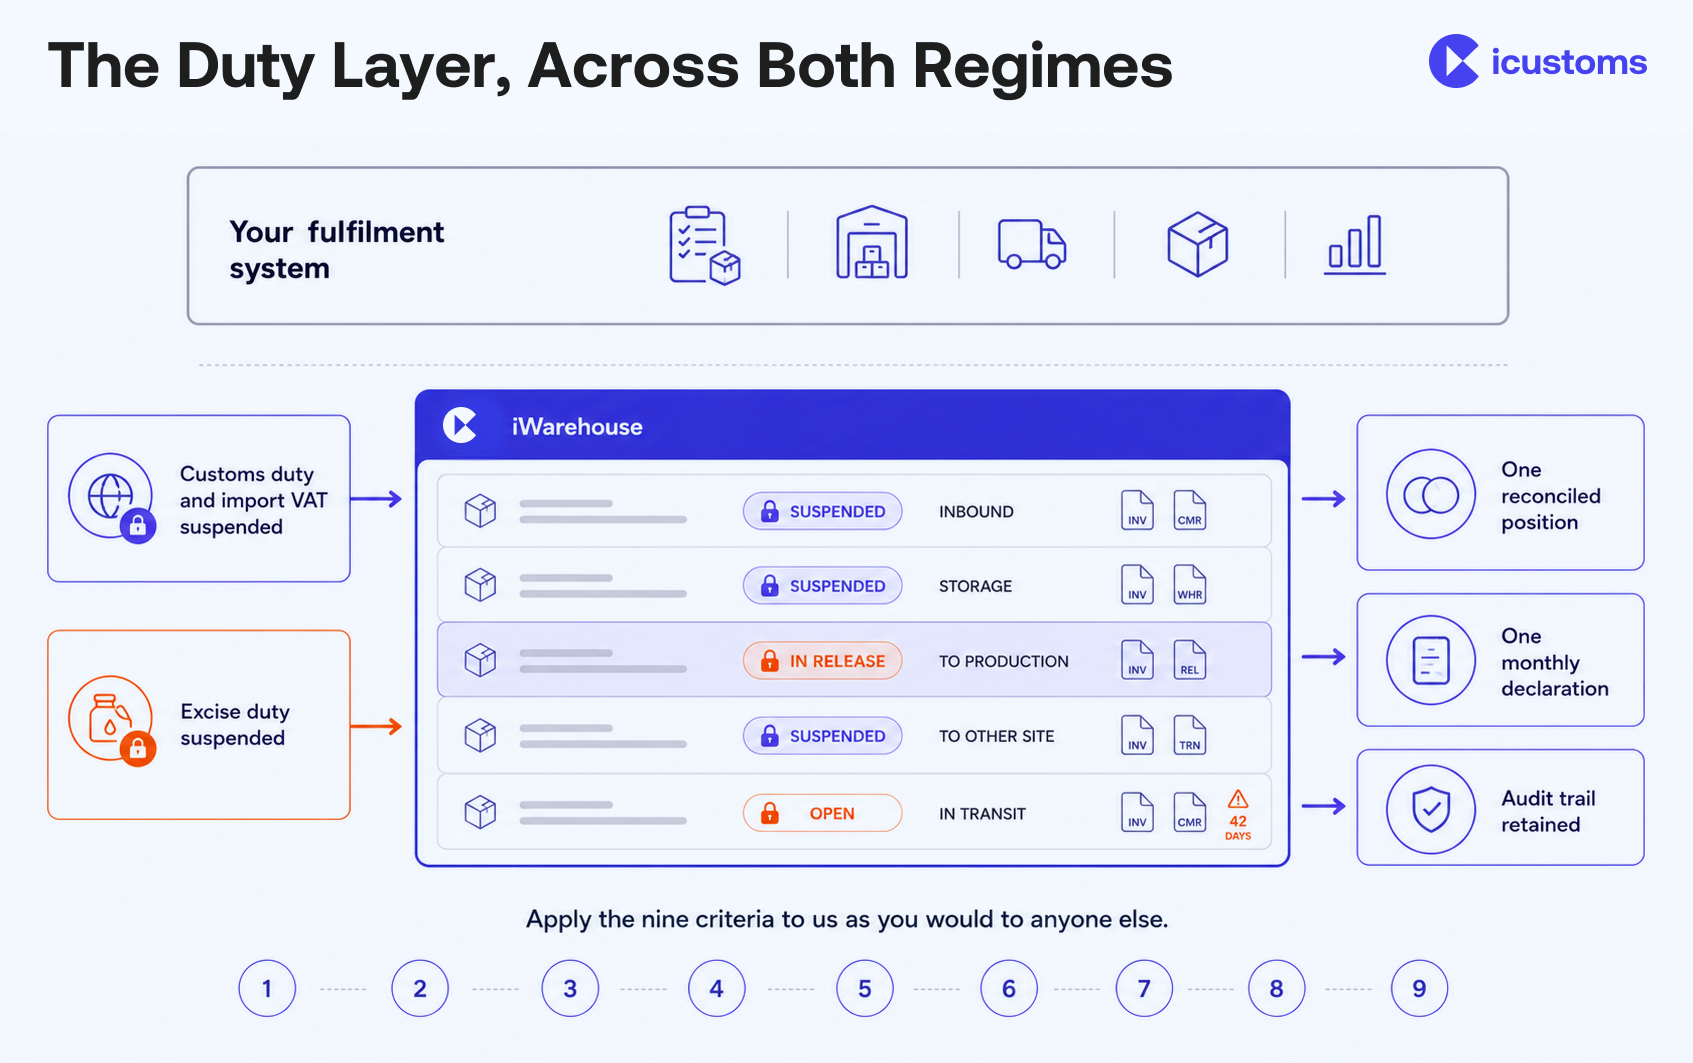
Honest positioning: iWarehouse is a duty layer product, not a fulfilment system. If what you need is picking, packing and carrier management, you need a warehouse management system and iWarehouse sits alongside it.
What it is built for is bonded storage operations across both regimes. It manages customs, bonded and excise warehouses from one AI platform, creates declarations automatically on arrival, lets you pay duty immediately or defer it in bond, holds duty status against stock so suspended and released positions stay distinct, attaches supporting documents to the consignment they belong to, and accounts for removals in one monthly declaration rather than shipment by shipment. Every action lands in a secure audit trail, with a compliance dashboard across every consignment.
Apply the nine criteria to it as you would to anyone else. The reason this guide is criteria-led rather than a ranked list is that a genuinely useful evaluation framework survives the market changing, and a ranked list does not.
Two natural next steps. If you are building the business case, our duty deferral and cash flow guide works through the numbers. If you are weighing this against carrying on as you are, see software against manual Excel records.
What this guide does not cover: cost
Deliberately. Pricing in this category varies by volume, number of premises, regimes covered, integration complexity and support tier, and a single figure would mislead more than it helps. Pricing models, what drives cost up or down, and the questions to ask during procurement are covered properly in our bonded warehouse software pricing guide. Treat any vendor quoting a headline price without asking about your volumes and regimes with caution.
Frequently Asked Questions
What features should bonded warehouse software have?
At minimum: a stock account that shows the current position in real time, duty status enforced per consignment rather than editable, distinct movement types each with their own evidence requirements, visibility of undischarged duty-suspended movements, documents attached to the consignments they relate to, owner and ownership change records, and a retrievable audit trail lasting at least four years after discharge.
Does bonded warehouse software integrate with my ERP?
Most claim to, so ask about mechanism and direction rather than accepting the claim. Your finance system needs the duty position and the duty system needs purchase and sales data. A monthly CSV export is not integration. Also ask about CDS for declarations, EMCS for duty-suspended excise movements, and your warehouse management system if you run one.
How much does customs warehouse software cost?
It varies by volume, number of premises, whether you need customs only or customs and excise, integration complexity and support level. There is no meaningful single figure, which is why pricing models and cost drivers are covered in a separate pricing guide rather than summarised here.
Can one platform manage customs and excise warehousing together?
Yes, though fewer products do than claim to. It matters because businesses importing alcohol, tobacco or energy products often need both approvals on the same premises. Running two systems means reconciling them manually, which reintroduces the error the approvals were meant to remove. Ask to see one reconciled position across both regimes, not two modules.
Does HMRC have to approve my bonded warehouse software?
For customs warehousing, HMRC guidance states that software which has not been approved cannot be used, and a duty management system that does not meet the requirements will not be approved. Note carefully that the responsibility and accuracy of the system lies with the warehousekeeper, not the supplier, so no purchase transfers that accountability.
What is the difference between a warehouse management system and bonded warehouse software?
A warehouse management system tracks locations, picks and despatch. Bonded warehouse software tracks duty status, procedure, declarations and the stock account. HMRC names both separately in its application requirements and asks applicants to include both if they use both, and treats commercial records plus the duty management system as one system constituting the stock account.
You may also like:
Struggling to Extract, Catagorise & Validate Your Documents?
Capture & Upload Data in Seconds with AI & Machine Learning
Subscribe to our Newsletter
About iCustoms
iCustoms is an all-in-one solution helping businesses automate customs processes more efficiently. With AI-powered and machine-learning capabilities, iCustoms is designed to streamline your all customs procedures in a few minutes, cut additional costs and save time.
Struggling to Extract, Catagorise & Validate Your Documents?
Capture & Upload Data in Seconds with AI & Machine Learning