

Alcohol Duty Warehousing: A Guide for Producers and Importers
- John Hall
- Customs Specialist at iCustoms.ai
An alcohol excise warehouse UK businesses use is premises approved by HMRC to hold alcoholic products in excise duty suspension. Producers may be able to hold their own output under a producer approval instead. Importers of finished alcohol cannot, and need excise warehousing.
That single distinction decides most of what follows, and it is the thing most guidance leaves implied rather than stated. This page splits into two tracks. Producers, meaning breweries, distilleries, cider makers and winemakers, have a genuine choice of route and access to reliefs based on how much they make. Importers have no choice of route but more access to relief than they usually realise. Both tracks need the same duty arithmetic, so that comes first.
The two routes: producer approval or excise warehouse
Bonded warehouse alcohol arrangements in the UK run through one of two approvals, and which applies to you depends on whether you make the product or buy it in.
Producers. An alcoholic products producer approval can carry authorisation to receive, store and dispatch alcoholic products in duty suspension. For a brewery or distillery holding its own output, that can remove the need for a separate excise warehouse approval. What it authorises varies, so read your own approval rather than assuming scope.
Importers. There is no producer approval available to a business that does not produce. If you buy in finished wine, spirits or beer and hold it, HMRC bonded storage under an excise warehouse approval is the route to duty suspension. Nothing in the alcohol duty reforms changed this.
The authorisation question itself, including the application route, the fit and proper test and what an APPA does and does not remove, is covered in full in our excise warehouse authorisation guide. This page assumes you know which route applies and deals with the duty, the reliefs and the day-to-day of each vertical.
How Alcohol Duty is calculated: strength bands
Since the alcohol duty reform, all alcoholic products are taxed on litres of pure alcohol rather than on product volume. You calculate the pure alcohol content, then apply the rate for that product category and strength band. The alcohol strength bands are shared across categories, but the rate attached to each band is not.
Rates below are per litre of pure alcohol, current from 1 February 2026.
| ABV Band | Beer | Still Cider | Sparkling Cider | Spirits | Wine | Other Fermented |
|---|---|---|---|---|---|---|
| 0 to 1.2% | £0.00 | £0.00 | £0.00 | £0.00 | £0.00 | £0.00 |
| 1.3 to 3.4% | £9.96 | £9.96 | £9.96 | £9.96 | £9.96 | £9.96 |
| 3.5 to 5.5% | £22.58 | £10.39 | £10.39 | £26.61 | £26.61 | £26.61 |
| 5.6 to 8.4% | £22.58 | £10.39 | £26.61 | £26.61 | £26.61 | £26.61 |
| 8.5 to 22% | £30.62 | £30.62 | £30.62 | £30.62 | £30.62 | £30.62 |
| Over 22% | £33.99 | £33.99 | £33.99 | £33.99 | £33.99 | £33.99 |
Two features of that table are worth pulling out, because they change commercial decisions and almost nobody states them.
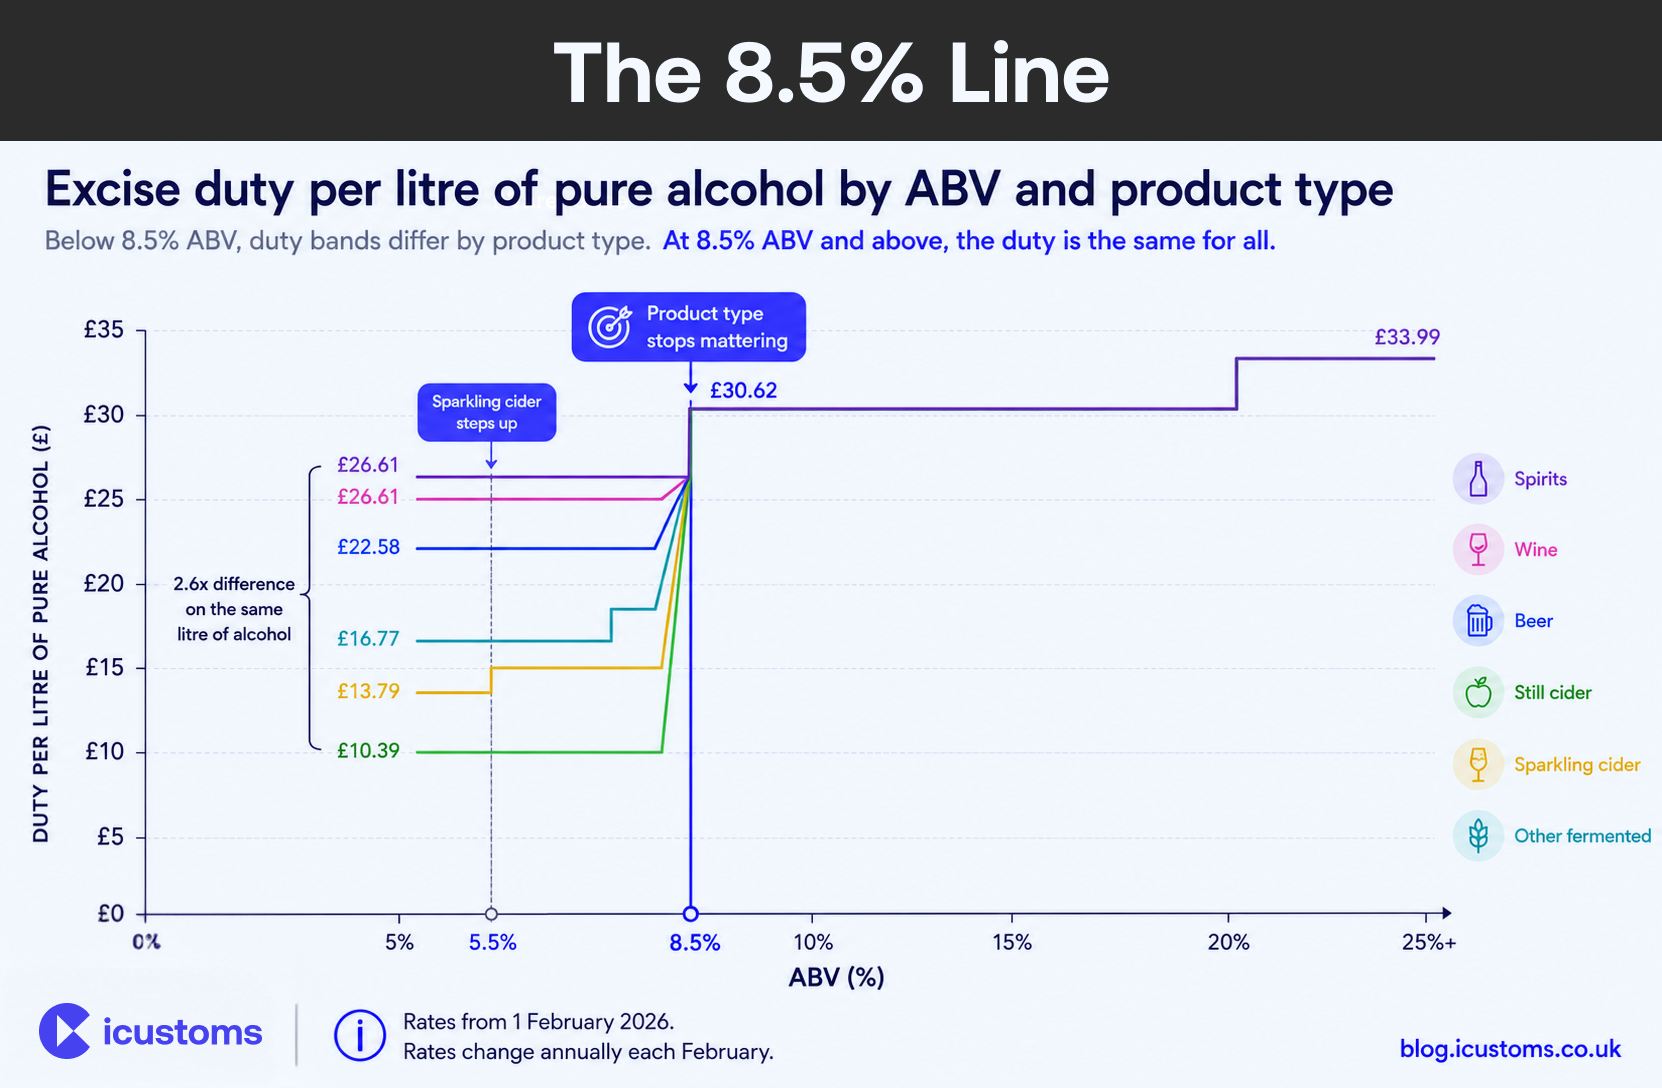
Below 8.5% ABV, product category matters enormously. Still cider at 4% pays £10.39 per litre of pure alcohol. Beer at the same strength pays £22.58. Wine or a spirit-based product pays £26.61. That is a spread of more than two and a half times on the same litre of alcohol, decided purely by what the product legally is.
At 8.5% and above, category stops mattering at all. Everything converges on £30.62, then £33.99 above 22%. A fortified wine, a cream liqueur and a cask-strength whisky are taxed identically per litre of pure alcohol. For anyone modelling a product portfolio, the 8.5% line is the single most important number in UK alcohol duty.
Small Producer Relief, and the timing trap that catches warehouses
Small Producer Relief is producer-only. It discounts your duty rate based on how much pure alcohol you produce annually, measured in hectolitres across all your products, using the previous production year or an estimate if you are new.
The mechanism is a set of lookup tables split by product category, strength band and whether the product is sold on draught. Each has seven bands with a marginal and a cumulative discount. You take your production figure, find your band, subtract the band start threshold, multiply by the marginal discount, add the cumulative discount, then divide by your production amount. That gives your discount per litre of pure alcohol, which you subtract from the full rate.
HMRC’s own worked example makes it concrete. A producer making 105 hectolitres of pure alcohol a year, selling draught beer at 3.4% ABV, lands in band 4 of the relevant table. Band start threshold 100, marginal discount 44 pence, cumulative discount £206.50.
- 105 minus 100 = 5
- 5 x 44 pence = £2.20
- £2.20 plus £206.50 = £208.70
- £208.70 divided by 105 = £1.99 discount per litre of pure alcohol
- Full draught rate £8.58 minus £1.99 = £6.59 per litre of pure alcohol
The timing rule that turns this into a records problem
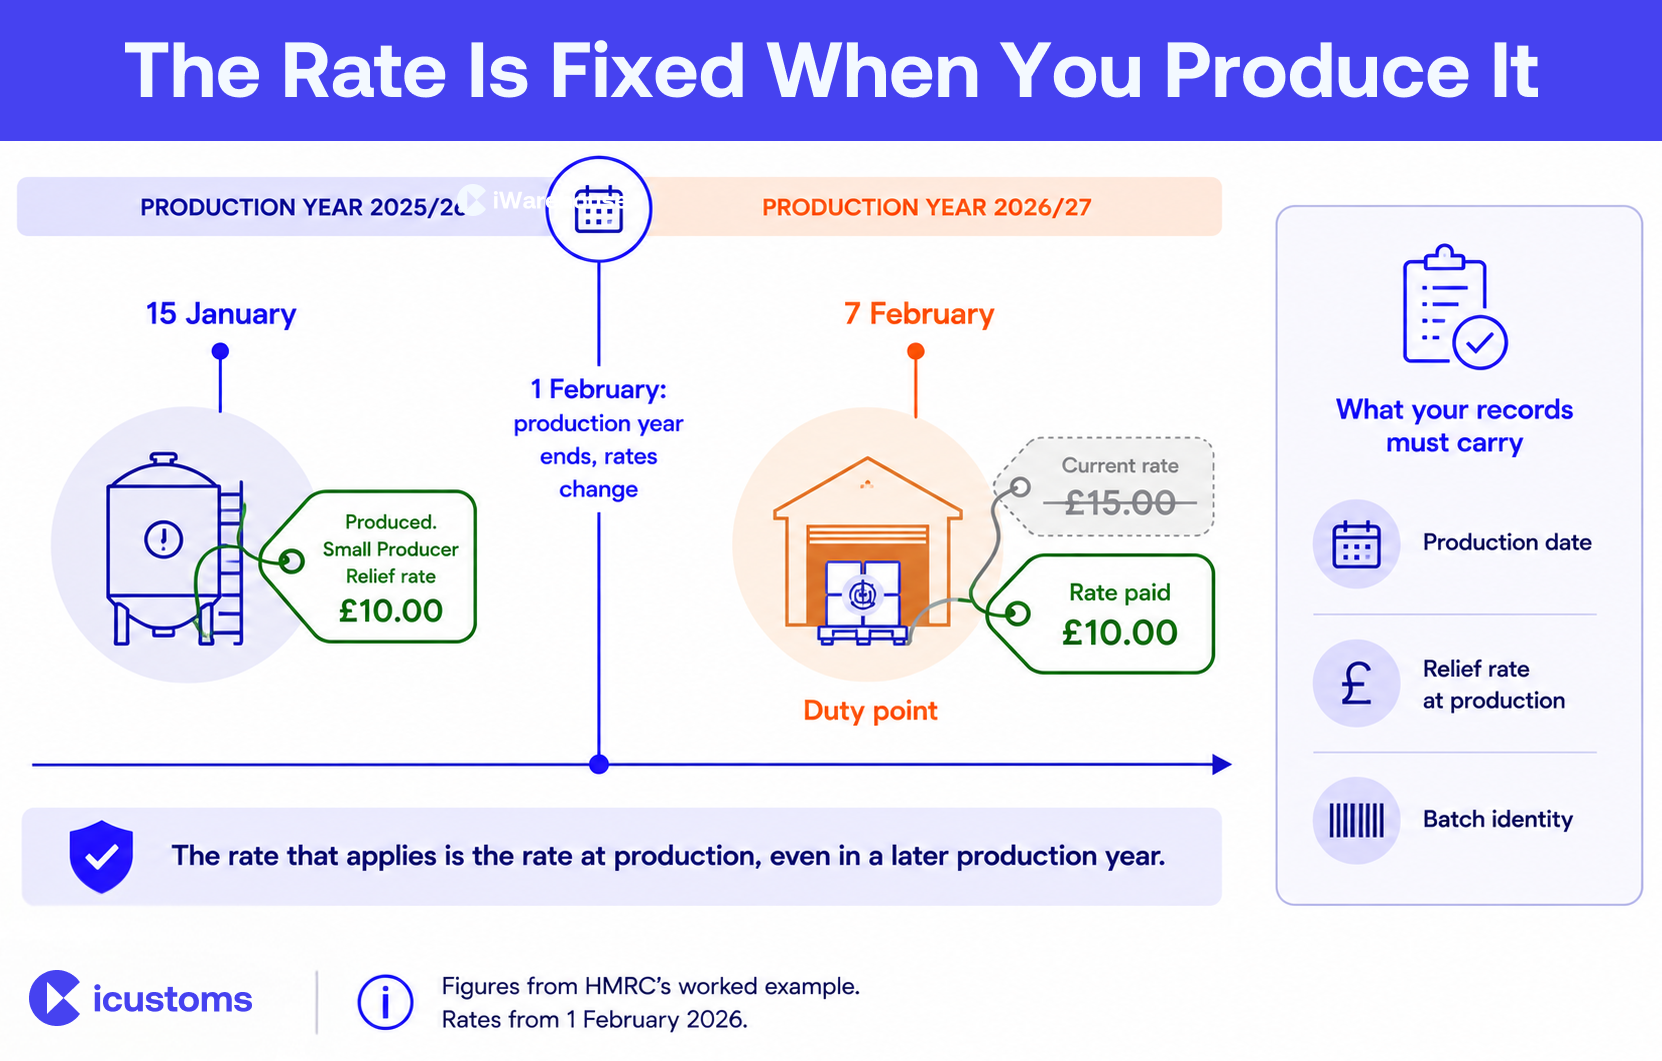
HMRC is explicit: you must apply the Small Producer Relief rate from the time the product was PRODUCED, not the rate in place when it passes the duty point. This holds even if the duty point falls in a different production year. HMRC’s example: a product made on 15 January carries an SPR rate of £10.00. It passes the duty point on 7 February, in the next production year, when the rate has risen to £15.00. The rate payable is £10.00. For anyone holding stock in bond across a February, this means the correct duty depends on a production date that may be years in the past. Your stock account has to carry it per batch, or you cannot calculate the duty correctly.
That rule is the reason brewery duty suspension and distillery stock records need to be batch-level rather than product-level. A spreadsheet that tracks how much whisky you hold, but not which production year each cask came from and what rate applied then, cannot produce a defensible duty figure on release.
Draught Relief, and why importers can claim it too
This is the most under-reported relief in UK alcohol duty, because most content treats it as a producer benefit. HMRC states plainly that you may be able to pay the reduced rate if you are a producer, an excise warehousekeeper, or an importer.
Eligible products are beer, cider including perry, spirits including spirit-based ready-to-drink products, wine including sparkling and fortified, and other fermented products such as fruit ciders. The product must be under 8.5% ABV. At the duty point it must either be packaged in eligible draught containers, or be going to a place in the UK to be transferred into them.
| Draught product | Rate per litre of pure alcohol | Full rate for comparison |
|---|---|---|
| All products under 3.5% | £8.58 | £9.96 |
| Still cider 3.5% to under 8.5% | £8.95 | £10.39 |
| Sparkling cider 3.5% to 5.5% | £8.95 | £10.39 |
| Sparkling cider over 5.5% | £19.45 | £26.61 |
| Beer, spirits, wine and other fermented 3.5% to under 8.5% | £19.45 | £22.58 (beer), £26.61 (others) |
The container test is specific and unforgiving. Your container must hold 20 litres or more and be able to connect to either a pump system or a gas pressurised drinks tap. Fail either condition and the full rate applies.
Two traps follow. Repackaging draught product into non-draught containers, decanting a keg into bottles for example, removes the reduced rate. You may only do it at all if you are an approved producer or an excise warehousekeeper, and only where full duty has been paid, with a penalty risk otherwise. Where an approved operator does repackage, the difference has to be declared as an underdeclaration in a previous period. Separately, if eligible draught product is supplied at the full rate for takeaway sales, you declare that using the underdeclaration box and must pass evidence that full duty was paid along the supply chain.
The producer track: breweries, distilleries and cask stock
For producers the practical question is not usually which approval to hold but how to handle stock that sits for a long time.
Distilleries feel this hardest. Whisky matures for years, and a whisky bond exists precisely so that duty is not funded across a maturation period that can run to a decade or more. A whisky bonded warehouse holding maturing spirit is doing something no other warehouse type does: carrying a duty liability that grows as the spirit concentrates and shrinks as it evaporates, against a rate that will change many times before release.
That makes batch, lot and cask tracking a compliance requirement rather than a nicety. Each cask needs its own identity, its production date, its strength at fill and at check, its location, and the relief position that applied when it was made. Aggregate stock figures cannot answer a question about a single cask, and a single cask is exactly what HMRC will ask about.
Breweries and cider makers face the same rule on a shorter cycle. Production years turn over every February, Small Producer Relief bands recalculate against last year’s output, and stock produced before the change carries the older rate. A distillery excise warehouse and a brewery each need the same thing from their records: production date and relief position, held per batch, retrievable years later.
Movements between approved premises add a second layer, because duty-suspended movements have to be recorded electronically. Our guide to how EMCS works covers that side.

The importer track: wine, spirits and finished stock
Importers have less choice and more sequencing to manage. A wine bonded warehouse UK importers use has to deal with two tax regimes rather than one, because imported alcohol carries customs duty and import VAT as well as excise duty, and excise duty suspension only becomes available once the goods are in free circulation.
In practice that means the customs position is settled first, or handled in parallel through a customs warehouse approval on the same premises, before excise warehousing does its job. Wine importer bonded storage is therefore usually a dual-approval arrangement, which is why importers so often discover they need both approvals rather than one.
The alcohol warehouse customs declaration side is where most operational friction sits. Alcohol import and movement declarations have to agree with each other and with the stock account: what was declared on entry, what was received into bond, what moved between premises, and what was declared on release. A mismatch between the customs entry and the excise stock record is one of the easiest findings for HMRC to make and one of the hardest to explain after the fact.
Fine wine adds its own layer. Fine wine bonded warehouse storage requirements and costs are driven less by duty and more by condition: temperature and humidity control, vibration, provenance records, and the fact that stock may change ownership several times while sitting in the same bay. For a warehouse holding fine wine for multiple owners, the ownership record is as important as the duty record, because HMRC expects full details of owners storing goods on the premises to be available.
Requirements, costs and finding a bonded warehouse
Three questions come up constantly, so here they are answered directly.
Requirements to bond warehouse UK premises. Both the operator and the premises are approved. HMRC assesses whether the business is a genuine, commercially viable enterprise with a real need for the approval, and whether the people behind it are law abiding and responsible. Premises have to be secure and suitable, your accounting system has to satisfy HMRC, and financial security may be required. Since June 2022 there is no minimum throughput threshold, but you do have to demonstrate real economic need.
Alcohol bonded warehouse in UK prices. There is no published tariff, and anyone quoting a single figure is guessing. Third-party bonded storage is normally charged per pallet or per case per week, with additional handling, in and out, and compliance or documentation fees. Cost drivers are the duty value of the stock, whether special conditions are needed, throughput, and how much compliance work the operator absorbs on your behalf. Get quotes on a like-for-like basis including handling and reporting, not storage alone.
Finding the best alcohol bonded warehouse in UK terms. Searching for a list of UK bonded warehouses will not get you far, because HMRC does not publish a browsable public directory of approved premises. What you can do is ask a prospective operator directly which approval they hold and whether it covers your product category, then validate the excise identifier they quote you through the SEED register of excise operators.
Location follows the trade. Alcohol warehousing London serves the fine wine market and the airports, Scotland concentrates around distilling, and alcohol warehouse Northern Ireland arrangements carry an extra dimension because Northern Ireland businesses hold XI-prefixed excise identifiers and can move duty-suspended goods to EU member states, which Great Britain businesses cannot. Approval itself is national, so what varies locally is capacity, approved product types and price rather than the rules.
What the records have to carry
Pull the threads together and a specification appears that is unusually demanding compared with ordinary warehousing.
- Litres of pure alcohol, not just volume, because that is the tax base. Strength has to be held and maintained per batch.
- Production date and the relief position that applied then, because Small Producer Relief is fixed at production and may be claimed years later.
- Draught eligibility per line, because the same product in a 20 litre keg and in bottles attracts different rates, and repackaging changes the answer.
- Owner of the goods, and any change of ownership, because HMRC expects owner details to be available and stock can change hands while stationary.
- Alcohol warehouse inventory movements in and out, reconciled to both the customs entry and the excise record.
- Batch, lot and cask identity, so a question about one cask can be answered without reconstructing a year of paperwork.
That is what alcohol warehouse software has to do, and it is a different job from general warehouse management. A conventional system tracks units and locations. Alcohol warehouse management software has to track a tax base that changes with strength, a relief position fixed at a past date, and an ownership record that HMRC can ask about. The same applies whether you need wine warehouse management software for a multi-owner fine wine operation or whisky warehouse management software for maturing cask stock: the entity being tracked is a duty position, not a pallet.
iWarehouse is built for bonded storage operations rather than adapted from general warehousing. It holds the bonded stock position and movement history together, keeps duty status against stock, supports batch-level identity so production dates and relief positions travel with the goods, and reconciles the period so what you declare matches your records. You can manage alcohol duty suspension with iWarehouse across both the customs and excise sides of the same site.
If you are working out which approvals you need first, start with what a bonded warehouse is and then the excise warehouse authorisation guide.
Frequently Asked Questions
Do small breweries need a bonded warehouse?
Not necessarily. A brewery holding its own output may be covered by the appropriate authorisation under its alcoholic products producer approval, which can remove the need for a separate excise warehouse approval. Check what your own approval authorises. Small Producer Relief is a separate matter and reduces your duty rate based on annual production rather than affecting which approval you hold.
Does APPA remove the need for a wine importer to use a bonded warehouse?
No. A producer approval is only available to businesses that produce alcoholic products. A wine importer buying in finished wine produces nothing, so there is no producer route available and excise warehousing remains how that stock is held in duty suspension. This did not change with the alcohol duty reforms.
How is Alcohol Duty calculated in a warehouse?
On litres of pure alcohol. Multiply the volume by the ABV to get the pure alcohol content, then apply the rate for that product category and strength band. Rates run from £9.96 per litre of pure alcohol in the 1.3 to 3.4% band up to £33.99 above 22%, with draught and small producer rates lower where they apply.
What is Small Producer Relief?
A discount on your Alcohol Duty rate for producers, based on how much pure alcohol you make annually in hectolitres. You use HMRC lookup tables for your product category and strength band to work out a discount per litre of pure alcohol, then subtract it from the full rate. It is producer-only and not available to importers.
Can importers claim Draught Relief?
Yes. HMRC states the reduced rate may be available to a producer, an excise warehousekeeper or an importer. The product must be under 8.5% ABV and, at the duty point, either packaged in eligible draught containers holding 20 litres or more that connect to a pump or gas pressurised tap, or destined for transfer into them in the UK.
You may also like:
Struggling to Extract, Catagorise & Validate Your Documents?
Capture & Upload Data in Seconds with AI & Machine Learning
Subscribe to our Newsletter
About iCustoms
iCustoms is an all-in-one solution helping businesses automate customs processes more efficiently. With AI-powered and machine-learning capabilities, iCustoms is designed to streamline your all customs procedures in a few minutes, cut additional costs and save time.
Struggling to Extract, Catagorise & Validate Your Documents?
Capture & Upload Data in Seconds with AI & Machine Learning